PennsylvaniaInsurance Appraiser (844) 537-1427

Independent appraisal · All 67 counties

Pennsylvania Insurance Appraiser: a second, independent number for your property claim

When the insurer accepts the claim but the check won’t cover the repair, Pennsylvania Insurance Appraiser writes its own line-by-line valuation and carries it through the appraisal clause in your policy.

  • Your appointed appraiser
  • Homes, rentals, HOAs & commercial
  • Fee in writing up front

Free claim review

Is your settlement short?

Leave a number. We’ll call within one business day.

No obligation. Nothing is shared.

67Pennsylvania counties served
11Appraisal & estimating services
7Free claim calculators
2 of 3Signatures make an award binding

What we do

What a Pennsylvania Insurance Appraiser does — and doesn’t

Most underpaid claims in Pennsylvania aren’t denied. They’re short. A slate roof priced as asphalt, a rowhome flat roof patched on paper when it needs replacing, plaster walls written up as drywall, a frozen-pipe loss with half the tear-out missing. Pennsylvania Insurance Appraiser exists for the gap between “covered” and “paid in full.”

We value the loss from scratch — our own inspection, measurements and pricing — and we build numbers that hold up in front of an umpire. If your problem is really a coverage denial, a bad-faith question or a looming deadline, we’ll tell you on the first call that you need a Pennsylvania attorney instead.

Appraisal usually fits

  • Coverage accepted, cost disputed
  • Repair vs. replace arguments
  • Matching, slate and specialty materials
  • Missing trades, code items and O&P

It usually doesn’t

  • Outright coverage denials
  • Bad-faith or legal claims
  • Flood losses under a homeowner policy
  • Gaps too small to justify fees
About Pennsylvania Insurance Appraiser
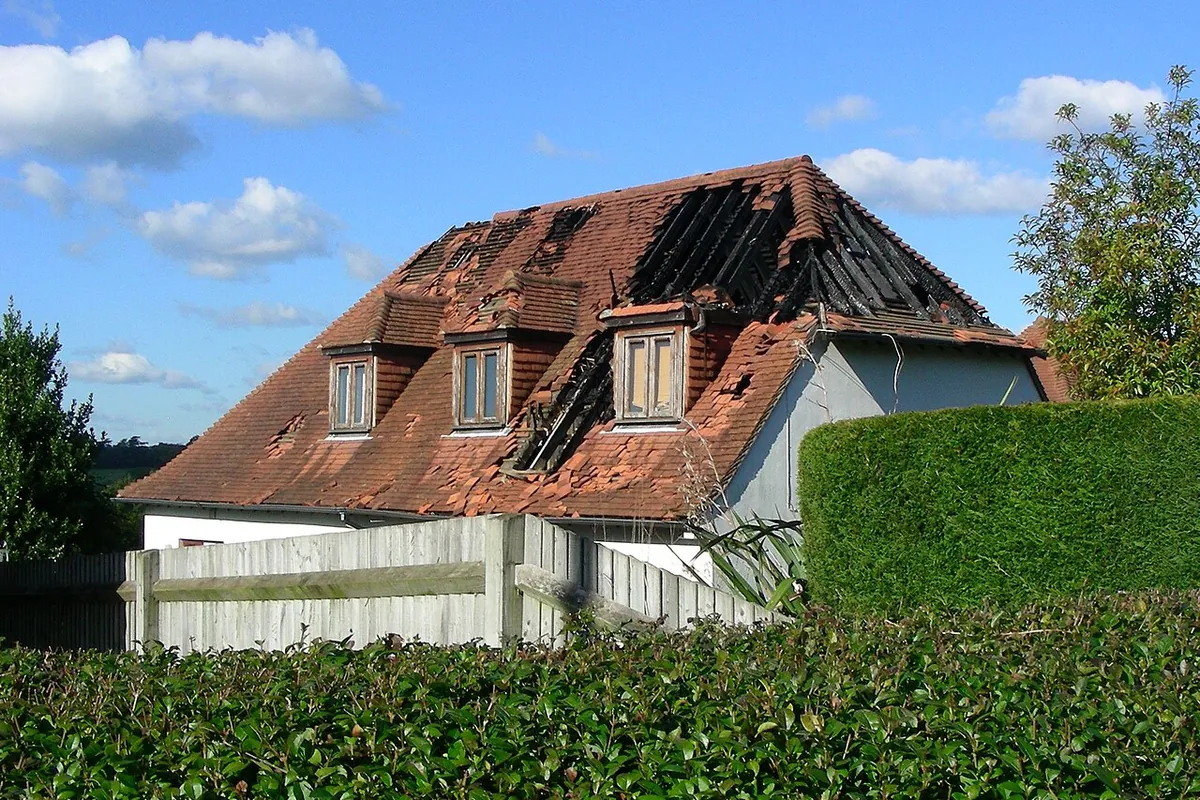
House with a fire-damaged roof and broken dormer windows awaiting repair
Every valuation starts with our own inspection, not an edited copy of the carrier’s estimate.

Services

Appraisal services from Pennsylvania Insurance Appraiser

11 services built around one job: a valuation of your loss that holds up. Start with an estimate review, or bring us in after appraisal has been demanded.

01

Appraisal Demand Representation

We act as your chosen appraiser after you or your insurer makes a written appraisal demand.Learn more
02

Homeowner Claim Appraisal

Appraisal for houses, rowhomes, twins and condo units when the insurer's number leaves you short.Learn more
03

Commercial & HOA Appraisal

Appraisal for businesses, condo associations, HOAs and multifamily owners with large or complex losses.Learn more
04

Roof & Hail Damage Appraisal

Appraisal for disputed roof claims: hail, wind, slate, flat rowhome roofs, metal and asphalt.Learn more
05

Wind & Tornado Appraisal

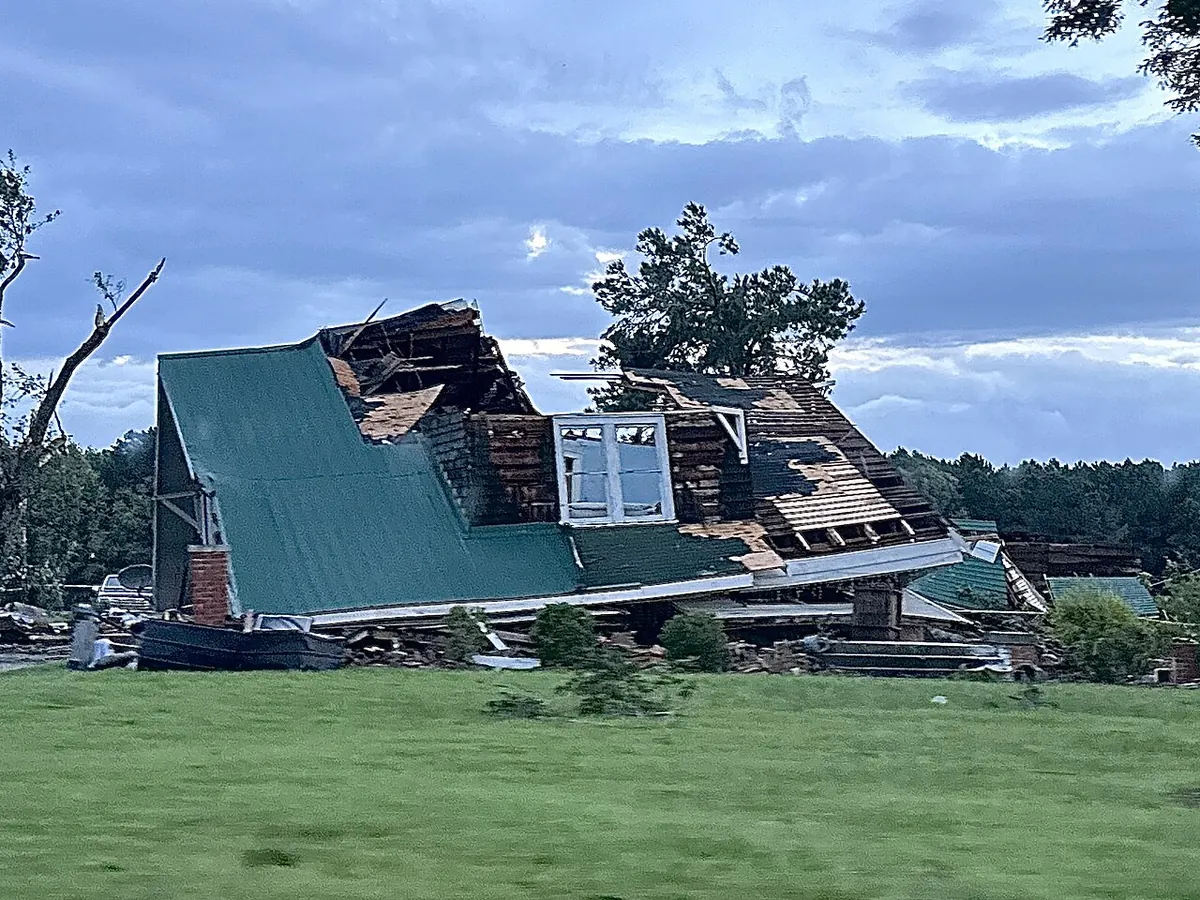
Appraisal for thunderstorm wind, straight-line wind, tornado and fallen-tree damage across Pennsylvania.Learn more
06

Tropical Storm Remnant Appraisal

Appraisal for claims from hurricane remnants: wind-driven rain, fallen trees and the flood vs. wind split.Learn more
07

Water Damage Claim Appraisal

Appraisal for sudden water losses from leaks, appliance failures, roof openings and plumbing breaks.Learn more
08

Fire & Smoke Damage Appraisal

Appraisal for fire, smoke and soot losses, including rebuild cost, cleaning scope, contents and ALE.Learn more
09

Ice Dam & Frozen Pipe Appraisal

Appraisal for winter losses: ice dams, burst pipes, snow-load collapse and lake-effect storm damage.Learn more
10

Insurance Estimate Review

A line-by-line review of your insurer's estimate that shows what is missing, underpriced or misapplied.Learn more
11

Umpire & Neutral Services

Neutral umpire services for Pennsylvania appraisal panels that cannot reach agreement on their own.Learn more

Compare all services

Pennsylvania’s claim year

The four seasons a Pennsylvania Insurance Appraiser plans around

Pennsylvania weather sends a different kind of claim every quarter. Knowing what each season does to a roof, a pipe or a basement is half of writing an accurate estimate.

Winter

Dec – Mar
  • Burst and frozen pipes
  • Ice dams and attic leaks
  • Snow-load collapse
  • Ice storms and fallen limbs

The Blizzard of 1993, the January 1996 blizzard, the February 2010 storms and Erie’s Christmas 2017 lake-effect snow all left roof and water claims behind.
Spring

Apr – Jun
  • Hail and severe storms
  • Tornadoes
  • Flash flooding
  • Roof wind damage

Western Pennsylvania’s May 31, 1985 tornado outbreak and Agnes in June 1972 are the reminders every adjuster in the state knows.

Summer

Jul – Sep
  • Tropical storm remnants
  • Lightning fires
  • Downbursts and trees
  • Water through roofs

Remnants of Ivan (2004), Lee (2011), Ida (2021) and Debby (2024) showed how much rain a fading tropical system can drop inland.

Fall

Oct – Nov
  • Nor’easters and wind
  • Clogged gutters and leaks
  • Early freezes
  • Power-outage losses

Superstorm Sandy in October 2012 brought hours of wind, fallen trees and long outages across the eastern half of the state.

How it works

From first call to signed award with Pennsylvania Insurance Appraiser

The appraisal clause turns an open-ended argument into a defined process with a binding result. Here is how a file moves.

  1. 1

    Free review

    We read the policy, the carrier’s estimate and your photos, then tell you plainly whether appraisal fits.

  2. 2

    Our own scope

    A Pennsylvania Insurance Appraiser inspects, measures and writes a line-item estimate priced for your area.

  3. 3

    Written demand

    Appraisal is demanded in writing and your appraiser is named, with the suit-limitation date in view.

  4. 4

    Panel work

    Both appraisers compare scope and pricing line by line. Most of the gap is settled here.

  5. 5

    Signed award

    An umpire decides anything left. Two of three signatures set the amount of loss.

Read the full appraisal process, step by step

Quick gap check

Is your gap big enough for a Pennsylvania Insurance Appraiser?

Type in the two numbers you already have. A large difference is worth a conversation; a small one may close faster with a documented supplement request.

The full claim gap & fee projector adds appraiser and umpire fees so you see a realistic net.

All 7 free calculators
Quick gap checkNo sign-up
50%
of the disputed amount
Amount in dispute$0
Gap vs. carrier estimate—
Projected award$0
Increase before fees$0

Statewide

Six regions, one Pennsylvania Insurance Appraiser

A flat roof in South Philly, a slate roof in Scranton’s Hill Section and a bank barn outside Lancaster fail in different ways. Here is how claims differ across the state.

Southeastern PA

Philadelphia and the collar counties: rowhome flat roofs, party walls, burst pipes in old housing and the Ida-era split between flood and covered water.

Lehigh Valley & Berks

Allentown and Reading: brick rows, twins, warehouses and the limestone sinkhole question that sits under parts of the valley.

Northeastern PA

Scranton, Wilkes-Barre and the Poconos: heavy snow, river flooding history and the coal-region mine subsidence issue.

South Central PA

Harrisburg, Lancaster and York: Susquehanna flooding history, stone farmhouses, bank barns and spring hail.

Central PA

State College and the ridge-and-valley country: student rentals, ice storms and wind funnelled along the ridges.

Western PA

Pittsburgh, Johnstown and Erie: hillside homes, flash floods in the hollows and lake-effect snow loads.

Cities we visit most

See every area we serve

Choosing help

Appraiser, public adjuster or attorney?

Each one solves a different problem. Picking the right one first saves time and fees, and Pennsylvania Insurance Appraiser will point you elsewhere when appraisal isn’t the tool.

You are here

Pennsylvania Insurance Appraiser

Main job
Value the amount of loss
Best stage
Coverage accepted, number disputed
Result
Award signed by two of three

Public adjuster

Main job
Prepare and negotiate the whole claim
Best stage
Early, soon after the loss
Result
Negotiated settlement

Attorney

Main job
Coverage, bad faith, litigation
Best stage
Denials and close deadlines
Result
Settlement or judgment

Before you sign the release

Check the numbers with a Pennsylvania Insurance Appraiser first

A short review now can keep you from accepting a settlement that won’t cover the repair — and from missing a one-year suit date while you argue about it.

FAQ

Questions people ask a Pennsylvania Insurance Appraiser

Straight answers on how appraisal works, what it costs and when it’s the wrong move.

What does a Pennsylvania Insurance Appraiser do?

We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, write an independent line-item estimate, work with the carrier’s appraiser and, if needed, take unresolved items to a neutral umpire.

Is appraisal the same as hiring a public adjuster?

No. A public adjuster, licensed by the Pennsylvania Insurance Department, handles and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.

When should I call a Pennsylvania Insurance Appraiser?

When coverage is accepted, you have the carrier’s estimate, and the gap between it and a contractor’s line-item estimate is meaningful — often more than about 10% or several thousand dollars.

Does appraisal stop my one-year suit deadline?

Not automatically. Many Pennsylvania policies limit lawsuits to one year from the date of loss, and appraisal may not pause that clock unless the policy or a written agreement says so. If the date is close, talk to a Pennsylvania attorney.

What does it cost?

Each side pays its own appraiser and usually half of the umpire. We put our fee in writing before any work starts, and the first conversation is free.

Do you cover my county?

Yes. We work in all 67 Pennsylvania counties, with frequent work around Philadelphia, Pittsburgh, the Lehigh Valley, Harrisburg, Lancaster, Scranton and Erie.

Guides

Read this before you demand appraisal

Practical guides from Pennsylvania Insurance Appraiser on Pennsylvania policy language, documentation and timing.

All policy & claim guides

Start with a conversation

Talk to Pennsylvania Insurance Appraiser about your claim

Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing — no pressure, no obligation.

Tell us about your claim

Free review, no obligation. We usually reply within one business day.

Call now Free review